How 2059 N Lorel Ave Chicago IL Defines Multifamily Investment Strategy in Belmont Cragin
Small multifamily pricing on Chicago’s Northwest Side keeps shifting, and pricing a two-flat wrong can cost you tens of thousands of dollars. The April 2026 sale of 2059 N Lorel Ave Chicago IL gives buyers, sellers, and investors a clean, recent benchmark. This updated 2-unit building sold for $490,000 after 85 days on the market. Six months later, automated valuation models place it anywhere from $488K to $577K. That spread is exactly where smart deal-making happens.
At Chicagoland Business Broker, we evaluated every public data point on this property. Our team combines business brokerage, on-site appraisals, and licensed real estate experience in Illinois. Below, we break down the numbers, the comps, the taxes, and the financing paths so you can price your next deal with confidence.
Key Takeaways
- Sold at 99% of list: The building closed at $490,000 on April 24, 2026, just 1.01% below its $495,000 list price.
- Valuations now range widely: Three AVMs cluster near $488K to $501K, while Redfin estimates $577,325. Use comps, not a single estimate, to set price.
- Taxes are a moving target: The total assessment jumped from $21,000 to $39,001 in 2023. Budget for reassessment risk before you buy any Cook County two-flat.
Property Snapshot: What Sold at 2059 N Lorel Ave
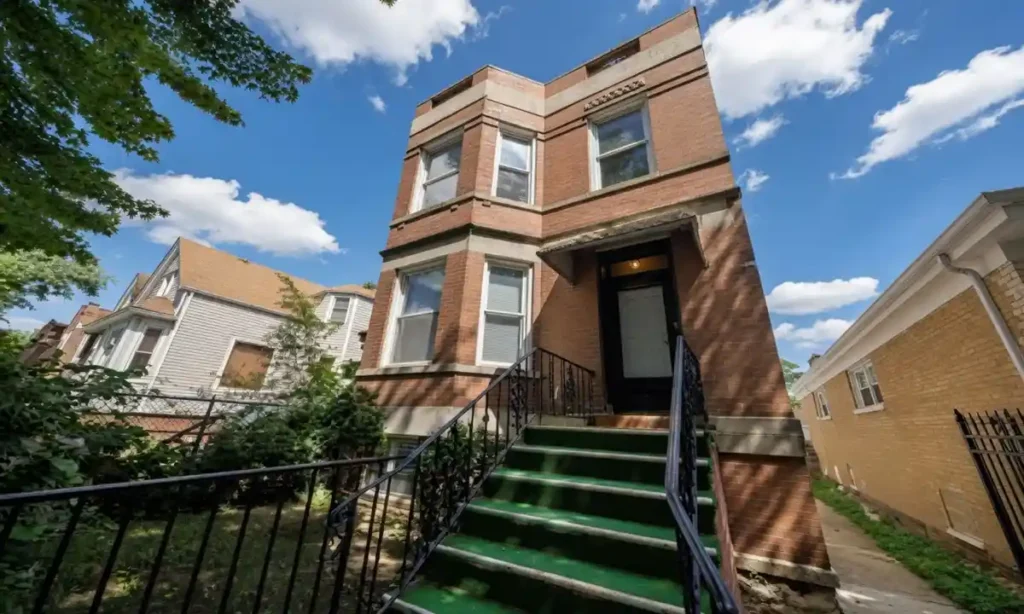
The property is a turn-key, fee-simple 2-unit building a half block north of Grand Avenue. It sits in Belmont Cragin, inside the Hanson Park pocket of ZIP code 60639. The listing highlighted new cabinetry, granite countertops, and stainless steel appliances in both units. Each unit also has its own laundry, a newer gas forced-air furnace, and central A/C.
| Feature | Detail |
|---|---|
| Address | 2059 N Lorel Ave, Chicago, IL 60639 |
| Property Type | Multi-Family, 2 Units (Fee Simple) |
| Beds / Baths | 6 Beds / 2 Full + 1 Half Bath |
| Total Rooms | 12 |
| Year Built | 1908 (100+ years) |
| Lot Size | 25 x 125 (3,125 sq ft) |
| Sale Price | $490,000 |
| Sale Date | April 24, 2026 |
| MLS # | 12554715 |
| APN (PIN) | 13331100260000 |
| Zoning (per Redfin) | RS-3, Residential Single-Unit (Detached House) |
| Annual Tax | $4,433 (2023 tax year) |
| Township | Jefferson |
| Parking | 2-Car Detached Garage |
| Basement | None |
| Exterior | Aluminum Siding, Fiber Cement |
| Utilities | Separate for each unit; Lake Michigan water; public sewer |
| Nearest Transit | Hanson Park Metra (Milwaukee District West) |
One detail deserves attention: RS-3 zoning is designed for single-unit detached houses. Many older Chicago two-flats operate as legal nonconforming uses. Always confirm the legal unit count with the City of Chicago before closing. You can review the full MLS record on the Redfin listing for this property.
Your next step: pull the zoning certification and building permit history for any two-flat you plan to buy.
Transaction Timeline: How the Deal Closed
The sale took 85 days from listing to closing. That timeline included two contingent periods and one return to active status. Our hands-on deal analysis suggests the first contract fell through within days, likely during inspection or financing review.
| Date | Event | Price |
|---|---|---|
| Mar 4, 1994 | Prior Sale (Public Record) | $65,000 |
| Jan 28, 2026 | Listed (Active) | $495,000 |
| Feb 5, 2026 | Contingent (Continue to Show) | |
| Feb 9, 2026 | Relisted (Active) | |
| Mar 29, 2026 | Contingent (Continue to Show) | |
| Apr 24, 2026 | Sold (Closed) | $490,000 |
| Deal Metric | Value |
|---|---|
| List-to-Sale Discount | 1.01% |
| Days from List to Close | 85 |
| Days from Second Contract to Close | 26 |
| Price Growth Since 1994 | +653.8% ($65K to $490K) |
| Finance Type | Conventional |
| Possession | At Closing |
| Listing Brokerage | Charles Rutenberg Realty of IL |
| Buyer Brokerage | Avenue Properties Chicago |
A “continue to show” contingency lets sellers collect backup offers. That strategy kept momentum alive here. When the first deal collapsed, the seller relisted in four days and held the price near ask. Chicagoland dealmakers are noting this pattern across well-updated two-flats in 60639: buyers still pay close to ask for move-in-ready income property.
Your next step: if you’re selling, ask your broker to structure contingencies so the property stays visible to backup buyers.
Unit-by-Unit Breakdown
The two units serve different renter profiles. One is a compact 2-bedroom; the other is a family-sized 4-bedroom. That mix gives an owner-occupant a real choice between living small and renting large, or the reverse.
| Unit | Beds | Baths | Rooms | Tenant Pays | Features |
|---|---|---|---|---|---|
| Unit 1 | 2 | 1 Full | 5 | Electric, Gas, Heat | Stove, Refrigerator, In-Unit Laundry, Gas FA Furnace, A/C |
| Unit 2 | 4 | 1 Full + 1 Half | 7 | Electric, Gas, Heat | Stove, Refrigerator, In-Unit Laundry, Gas FA Furnace, A/C |
| Shared Building Feature | Investor Impact |
|---|---|
| Separate Utilities | Tenants carry heat and electric costs, protecting net operating income |
| Large Yard | Appeals to families and longer-term tenants |
| 2-Car Garage | Potential ancillary income if rented separately |
| Built Before 1978 | Federal lead-based paint disclosure required for leases and sales |
| No Basement | Fewer water intrusion risks; no garden-unit conversion upside |
Separate utilities are one of the biggest value drivers in small multifamily. They shift the largest variable expense to tenants. That makes the income stream more predictable and easier for lenders to underwrite.
Note: the MLS also flags “3 BR units in building: Yes,” which conflicts with the 2-bed and 4-bed unit data. Buyers should confirm the bedroom count during a walk-through and appraisal.
Your next step: request current leases or a rent survey for each unit before you write an offer.
Valuation Comparison: 2026 Estimates
Automated valuation models (AVMs, computer-generated price estimates) disagree on this building by nearly $89,000. Three providers sit near the sale price. Redfin sits far above it. If you’ve been tracking Illinois property and business sales, this gap won’t come as a surprise. AVMs struggle with multifamily buildings because they rarely capture rent rolls or renovation quality.
| Source | Estimate (Oct 2026) | vs. $490K Sale Price |
|---|---|---|
| Quantarium | $488,243 | -0.4% |
| Collateral Analytics | $499,000 | +1.8% |
| Cotality | $501,368 | +2.3% |
| Redfin Estimate | $577,325 | +17.8% |
| Redfin Est. Sale Range | $549,000 to $664,000 | +12.0% to +35.5% |
| Valuation Insight | Data Point |
|---|---|
| Average of Three Realtor.com AVMs | $496,204 |
| Redfin Change Since Sale | +$87K |
| Redfin Change Since September 2026 | +$10K |
| Redfin vs. Comp Average ($439K) | 31.5% higher |
Realtor.com’s providers track closely with the actual closing price. You can compare them directly on the Realtor.com property page. At Chicagoland Business Broker, we treat AVMs as a starting point only. A true valuation of 2059 n lorel ave chicago il requires income analysis, comps, and an on-site condition review.
Income-Based Value Check
Investors price two-flats on capitalization rate (cap rate, net operating income divided by price). The table below shows the net operating income required to justify the $490,000 price at common cap rates.
| Target Cap Rate | NOI Needed at $490,000 | Monthly NOI Equivalent |
|---|---|---|
| 5.0% | $24,500 | $2,042 |
| 5.5% | $26,950 | $2,246 |
| 6.0% | $29,400 | $2,450 |
| 6.5% | $31,850 | $2,654 |
| 7.0% | $34,300 | $2,858 |
Your next step: plug in actual rents and expenses to see which cap rate this price really delivers.
Nearby Comparable Sales: 2026
Six recent sales near Lorel Avenue form Redfin’s comparable set. Their average price is $439,167, which is about $51K below the Lorel sale. The premium reflects the building’s full renovation, separate utilities, and in-unit laundry.
| Address | Sale Date | Price | Beds / Baths | Notes |
|---|---|---|---|---|
| 2139 N Long Ave | Mar 31, 2026 | $380,000 | 5 / 3 | Lowest comp in set |
| 2110 N Mango Ave | Jun 29, 2026 | $455,000 | 6 / 3 | Same bed count |
| 2109 N Lorel Ave | Aug 26, 2026 | $425,000 | 6 / 3 | Same street; Realtor.com lists $420K |
| 1801 N Lotus St | Sep 4, 2026 | $530,000 | 6 / 2 | Highest comp in set |
| 2209 N Long Ave | Sep 11, 2026 | $435,000 | 5 / 2.5 | Similar bath count |
| 2249 N Long Ave | Sep 24, 2026 | $410,000 | 4 / 2 | Smaller layout |
| Comp Statistic | Value |
|---|---|
| Average Sale Price | $439,167 |
| Median Sale Price | $430,000 |
| Price Range | $380,000 to $530,000 |
| 2059 N Lorel Premium vs. Average | +$50,833 (+11.6%) |
| Closest Match (Street + Size) | 2109 N Lorel Ave, $425,000 |
The closest comp, 2109 N Lorel Ave, also has six bedrooms. It sold for $65,000 less four months later. That gap shows how much renovation quality moves price on the same block. When we appraise a property like 2059 n lorel ave chicago il, we adjust each comp for condition, bath count, and parking.
Your next step: build your own comp grid with at least five sales from the past six months within a half mile.
Neighborhood Market Snapshot: Hanson Park and 60639
Hanson Park is currently a seller’s market, according to Redfin’s September 2026 data. Prices are still firm, though buyers negotiate more than they did a year ago. Three data sources give slightly different views of the same area.
| Metric | Value | Source Area |
|---|---|---|
| Median Sale Price | $427,000 | Hanson Park (Sept 2026) |
| Sale-to-List Ratio | 94.9% | Hanson Park (Sept 2026) |
| Avg. Days on Market | 42 | Hanson Park (Sept 2026) |
| Market Type | Seller’s Market | Hanson Park (Sept 2026) |
| Avg. Sale Price (12-Month) | $416,879 | Belmont Cragin |
| Avg. Days on Market (12-Month) | 47 | Belmont Cragin |
| Sale-to-List (12-Month) | 101% | Belmont Cragin |
| Median Listing Price | $449,950 | Northwest Side |
| Median Sold Price | $400,700 | Northwest Side |
| Median List Price per Sq Ft | $270 | Northwest Side |
| Days on Market | 26 | Northwest Side |
The 12-month Belmont Cragin average shows buyers paying 101% of list. The latest Hanson Park month shows 94.9%. That drop signals cooling negotiating power for sellers heading into late 2026.
Location Factors
| Factor | Rating / Distance |
|---|---|
| Hanson Park Elementary | 5/10, 0.4 mi |
| Northwest Middle School | 3/10, 0.2 mi |
| Foreman High School | 1/10, 1.5 mi |
| Groceries Score | 9/10 |
| Restaurants Score | 8/10 |
| Shopping Score | 8/10 |
| Flood Factor | 1/10 (Minimal) |
| Fire Factor | 1/10 (Minimal) |
| Heat Factor | 3/10 (Moderate) |
| Wind Factor | 2/10 (Minor) |
| Air Factor | 5/10 |
Your next step: price any 60639 listing off the most recent 90-day sale-to-list ratio, not the 12-month average.
Cook County Tax History
Property taxes on this building stayed near $4,200 to $5,600 for seven years. The bigger story is the assessment. In 2023, the total assessed value jumped 85.7%, from $21,000 to $39,001. Taxes rose only modestly that year, but higher assessments often show up in later bills.
| Year | Taxes | Total Assessment | Land | Additions (Building) |
|---|---|---|---|---|
| 2023 | $4,433 | $39,001 | $5,828 | $33,173 |
| 2022 | $4,321 | $21,000 | $4,725 | $16,275 |
| 2021 | $4,225 | $21,000 | $4,725 | $16,275 |
| 2020 | $4,520 | $20,282 | $3,937 | $16,345 |
| 2019 | $4,741 | $23,584 | $3,937 | $19,647 |
| 2018 | $4,661 | $23,584 | $3,937 | $19,647 |
| 2017 | $5,572 | $25,871 | $3,465 | $22,406 |
| Tax Insight | Value |
|---|---|
| 2023 Assessment Increase | +85.7% |
| 2023 Tax Increase | +2.6% |
| Effective Tax Rate on $490K Sale | 0.90% |
| Building Share of 2023 Assessment | 85.1% |
A 0.90% effective tax rate is low for Chicago. Buyers of 2059 n lorel ave chicago il should expect that rate to climb as the sale price and renovation filter into future assessments. Underwriting on the old tax bill is one of the most common mistakes we see.
Your next step: check the Cook County Assessor’s site for the latest reassessment notice on PIN 13331100260000 before you finalize your pro forma.
How 111 West Maple St Chicago IL Shapes Gold Coast Deal Strategy
How 2059 N Lorel Ave Chicago IL Defines Multifamily Investment Strategy in Belmont Cragin The April 2026 sale of 2059 N Lorel Ave Chicago IL gives buyers, sellers, and investors… @narcoblogger @123chicago @ChicagoREALTORS https://t.co/fABBYmoCbp
— Chicagoland Business Broker (@chicagoland55) October 15, 2026
Nearby Home Values on Lorel Ave
Neighboring properties on the 2000 block of Lorel show a wide value range. Larger multi-unit buildings estimate near $460K to $490K. Smaller single-family homes estimate near $290K to $340K.
| Address | Beds | Baths | Sq Ft | Estimate | Source |
|---|---|---|---|---|---|
| 2060 N Lorel Ave #1 | 4 | 2 | 2,408 | $488,095 | Redfin |
| 2066 N Lorel Ave | 4 | 2 | 2,408 | $481,340 | Redfin |
| 2051 N Lorel Ave #1 | 5 | 2 | 2,372 | $464,368 | Redfin |
| 2065 N Lorel Ave | 4 | 2 | N/A | $422,000 | Realtor.com |
| 2045 N Lorel Ave | 3 | 1.5 | 1,402 | $342,110 | Redfin |
| 2111 N Lorel Ave | 4 | 3 | N/A | $314,787 | Redfin |
| 2049 N Lorel Ave | 2 | 1 | 1,080 | $292,576 | Redfin |
The renovated building at 2059 n lorel ave chicago il sits at the top of the block by recorded sale price. That position matters for resale. Owners who renovate to the top of a block can struggle to push the next sale much higher.
Your next step: compare your target building’s estimate to the top three values on its block to spot overpricing.
Financing Options for 2-Unit Properties in Illinois
Two-unit buildings qualify for residential mortgage programs, which carry lower down payments than commercial loans. The biggest decision is whether you will live in one unit. Owner-occupants access far better terms than pure investors.
| Loan Type | Occupancy | Typical Minimum Down | Key Advantage | Key Limitation |
|---|---|---|---|---|
| FHA | Owner-occupied | 3.5% | Low down payment, flexible credit | Mortgage insurance; property must meet FHA standards |
| Conventional (Owner-Occupied) | Owner-occupied | 5% | No upfront MI; removable PMI | Stronger credit needed |
| VA | Owner-occupied (eligible veterans) | 0% | No down payment, no monthly MI | Eligibility required |
| Conventional (Investment) | Non-owner-occupied | 25% (2-unit) | Fixed-rate long-term debt | Higher rate and reserves |
| DSCR Loan | Investment | 20% to 25% | Qualifies on property income, not personal income | Higher rates and fees |
| Portfolio / Local Bank | Either | Varies | Flexible underwriting | Shorter terms, possible balloon |
How Lenders Count Rental Income
| Factor | What Lenders Typically Do |
|---|---|
| Rental Income Credit | Count about 75% of market or lease rent to offset vacancy and expenses |
| Appraisal Form | Small residential income property appraisal (Fannie Mae Form 1025) with rent schedule |
| Reserves | Require months of payments in reserve for multi-unit loans |
| Lead Paint | Pre-1978 buildings trigger disclosure and possible FHA paint condition repairs |
Buyer and Investor Action Steps
- Decide your occupancy plan before you shop for loans.
- Get preapproved with a lender experienced in Chicago two-flats.
- Request a rent schedule from your appraiser to confirm market rent for both units.
- Model taxes at reassessed levels, not the prior owner’s bill.
- Compare DSCR and conventional quotes if you are buying as a pure investor.
Our loan negotiation support at Chicagoland Business Broker helps buyers compare terms side by side. A property like 2059 n lorel ave chicago il fits several of these programs, which widens the buyer pool at resale.
Your next step: ask two lenders to quote the same scenario so you can compare rate, fees, and reserve requirements directly.
How 501 North Clinton Street Chicago IL Pricing Shapes Smarter Buy and Sell Decisions in 2026
Buyer vs. Seller Responsibilities
Each side carries specific obligations in an Illinois two-flat sale. Missing one can delay closing or reduce net proceeds.
| Task | Buyer | Seller |
|---|---|---|
| Earnest Money Deposit | ✓ | |
| Property Disclosure (Illinois Residential Real Property Disclosure) | ✓ | |
| Lead-Based Paint Disclosure (Pre-1978) | Acknowledges | ✓ |
| Home and Sewer Inspection | ✓ | |
| Appraisal and Loan Approval | ✓ | |
| Leases, Rent Roll, Security Deposits | Reviews | ✓ Provides |
| Tenant Estoppel Letters | Requests | ✓ Provides |
| Title Commitment and Survey | Reviews | ✓ Typically orders |
| Chicago Water Certification (Full Payment Certificate) | ✓ | |
| Zoning / Legal Unit Verification | ✓ | Supports |
| Security Deposit Transfer | Receives | ✓ Transfers with interest owed |
| Property Tax Proration | Credited | ✓ Credits buyer |
| Chicago Transfer Tax | ✓ (CTA and city buyer portion) | ✓ (state, county, and CTA seller portion) |
| Homeowner’s / Landlord Insurance | ✓ |
Chicago’s Residential Landlord and Tenant Ordinance governs security deposits and lease transfers. Deposit handling errors create real liability for both sides.
Your next step: create a shared closing checklist with your attorney at contract signing.
Pros and Cons of Investing in Belmont Cragin 2-Units
Belmont Cragin two-flats offer solid entry pricing compared to North Side neighborhoods. They also come with older housing stock and school ratings that some renters weigh heavily.
Pros
- Lower entry price: Median sales near $400K to $430K sit far below Logan Square or Lincoln Park.
- Owner-occupant financing: FHA and 5% down conventional loans apply to two-unit buildings.
- Strong daily amenities: Groceries score 9/10; restaurants and shopping score 8/10.
- Transit access: The Hanson Park Metra station connects to downtown on the Milwaukee District West line.
- Low climate risk: Flood and fire factors both rate 1/10.
- Tenant-paid utilities: Separately metered units protect cash flow.
- Steady demand: Buyers paid 101% of list on average over 12 months in Belmont Cragin.
Cons
- Aging buildings: Homes from the early 1900s need ongoing capital spending.
- Zoning questions: RS-3 zoning can complicate legal unit status and future conversion.
- School ratings: Foreman High School rates 1/10, which can limit some family renters.
- Tax uncertainty: Recent Cook County reassessments raised values sharply.
- Thin cap rates: Prices near $490K require strong rents to reach a 6% return.
- Cooling negotiations: Hanson Park sale-to-list fell to 94.9% in September 2026.
Your next step: weigh each con against your hold period and exit plan before committing capital.
2319 E 100th St Chicago IL: How Historic Stigma Shapes Valuation, Pricing, and Deal Strategy in 2026
Steps to Evaluate a Similar Deal
Evaluating a two-flat follows a repeatable process. We use this same framework when we value businesses with real estate attached, and when we appraise income property for clients.
- Verify the legal unit count with the City of Chicago zoning office and permit records.
- Collect leases and a rent roll for every unit, including deposit amounts.
- Build a comp grid of five or more sales within a half mile in the past six months.
- Calculate net operating income using real expenses: taxes, insurance, water, repairs, and vacancy.
- Stress-test property taxes at a reassessed value based on your purchase price.
- Order a full inspection covering roof, sewer line, electrical, and furnaces.
- Check lead paint and code compliance for pre-1978 construction.
- Run cap rate and cash-on-cash scenarios at three rent levels: low, expected, and high.
- Compare at least two financing quotes for rate, fees, and reserves.
- Set your walk-away price before you submit an offer.
Running this process on 2059 n lorel ave chicago il shows why a renovated building commands a premium: lower near-term capital spending, stronger tenant appeal, and easier financing.
Your next step: save this list as a checklist and apply it to the next three listings you review.
Frequently Asked Questions
What did 2059 N Lorel Ave sell for?
The building sold for $490,000 on April 24, 2026. It was listed at $495,000 on January 28, 2026, and closed 85 days later.
How many units and bedrooms does the property have?
It is a 2-unit building with 6 total bedrooms and 2.5 baths. Per MLS unit data, Unit 1 has 2 bedrooms and 1 bath, while Unit 2 has 4 bedrooms and 1.5 baths.
What is the property worth now?
Estimates vary. Realtor.com providers range from $488,243 to $501,368. Redfin estimates $577,325, with a projected sale range of $549,000 to $664,000. A professional appraisal gives the most reliable number.
Can I buy a building like this with a low down payment?
Yes, if you live in one unit. FHA loans allow 3.5% down, and conventional owner-occupied loans allow 5% down on two-unit properties. Investors usually need 20% to 25% down.
Are property taxes likely to rise?
The 2023 assessment rose 85.7%. Future bills may reflect the higher assessment and the 2026 sale price. Buyers should model taxes at reassessed levels.
Price Your Next Chicago Deal With Real Data
The sale of 2059 n lorel ave chicago il proves one point clearly: renovated, separately metered two-flats still sell near asking price in Belmont Cragin. The gap between AVM estimates and actual sales shows why real comps and income analysis beat any single online number.
At Chicagoland Business Broker, we bring 15+ years of business brokerage, 25+ years of healthcare practice sales, and licensed Illinois real estate experience to every engagement. We provide on-site appraisals, deal structuring, and loan negotiation support across Cook, Lake, DuPage, and McHenry Counties.