Homes for Sale Lincoln Park Chicago: How 2026 Pricing, Inventory, and Deal Strategy Impact Buyers, Sellers, and Business Owners
A $894,068 median sale price, up 24.2% year over year, changes the math for anyone shopping homes for sale Lincoln Park Chicago right now. That jump affects down payment size, jumbo loan exposure, and negotiating leverage for every buyer and seller in the 60614 zip code. For business owners planning an exit, it matters even more.
A home purchase timed poorly against a business sale can tie up liquidity, weaken an SBA loan application, or force a rushed deal. This guide shows the numbers first and the strategy second.
Key Takeaways
- Prices are climbing fast: Redfin reports a $894,068 median sale price for August 2026 (+24.2% YoY), while Fulton Grace shows an average home price near $1M at $604 per square foot.
- Inventory is tight but active: Roughly 195 listings on Fulton Grace and 108 homes plus 15 early access listings on Redfin, with an average of 45 days on market.
- Timing is everything for business owners: Coordinate your business sale, home purchase, and financing so one transaction strengthens the other instead of competing for the same cash and credit.
Why Lincoln Park Matters to Chicagoland Dealmakers
At Chicagoland Business Broker, we spend most of our time on business valuations, SBA loan negotiation, and deal structuring across Cook, Lake, DuPage, and McHenry Counties. But our clients rarely buy or sell a business in isolation. A liquidity event often triggers a home purchase, and a home purchase often affects personal financial statements that lenders review.
If you’ve been tracking Illinois business sales, this pattern won’t come as a surprise. Owners who close a practice or company sale frequently move toward lakefront neighborhoods, top school zones, and walkable commercial corridors. Lincoln Park checks all three boxes. That is why we track homes for sale Lincoln Park Chicago with the same discipline we apply to a cash flow analysis.
Lincoln Park Neighborhood Overview
Lincoln Park blends vintage architecture, new construction, and full-amenity high-rises on Chicago’s North Side. The neighborhood anchors around its 1,200-acre namesake park, the Lincoln Park Zoo, and DePaul University.
| Neighborhood Feature | What Buyers Get |
|---|---|
| Primary Zip Code | 60614 (some listings in 60657) |
| Green Space | Lincoln Park, Oz Park, Alfred Caldwell Lily Pool, Wrightwood Park |
| Anchor Institutions | DePaul University, Lincoln Park Zoo, North Pond |
| Retail Corridors | Armitage, Webster, Halsted, Clybourn, Southport, NEWCITY |
| Transit | Fullerton and Armitage CTA stops (Red/Brown lines), #64 and lakefront buses |
| Schools Named in Listings | Alcott, Prescott, Oscar Mayer, Lincoln Park High School |
| Historic Districts | McCormick Seminary Row House District (56 landmark homes) |
Our team observed that school district language appears in many of the strongest listings this fall. Listings that name Alcott, Prescott, or Oscar Mayer push that detail to the first line. That tells you exactly what buyers are paying for.
2026 Lincoln Park Market Snapshot
According to Fulton Grace’s Lincoln Park market page, the neighborhood averages $1M per home and $604 per square foot.
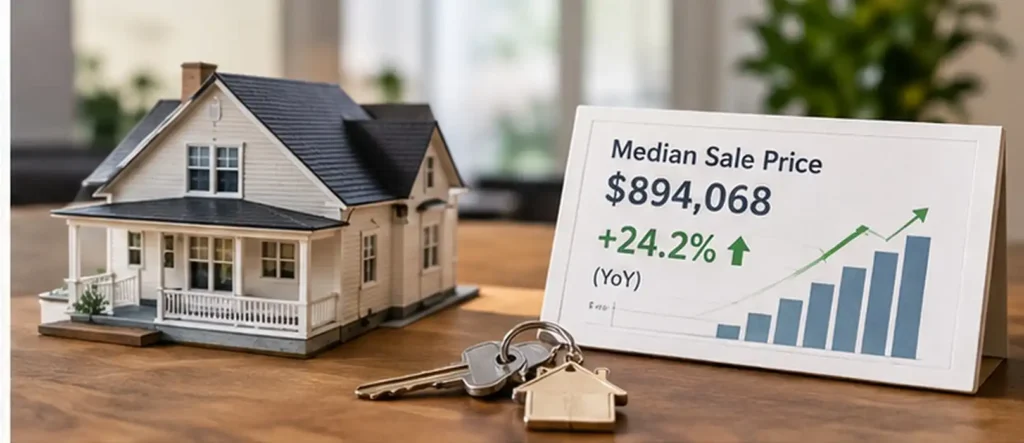
Meanwhile, the Redfin Lincoln Park neighborhood data shows double-digit annual growth in median sale price.
| Market Metric (Fall 2026) | Value | Source |
|---|---|---|
| Median Sale Price (Aug 2026) | $894,068 | Redfin |
| Year-over-Year Change | +24.2% | Redfin |
| Median Sale Price (May 2026) | $849,714 | Redfin (reported) |
| Average Home Price | ~$1,000,000 | Fulton Grace |
| Average Price per Sq. Ft. | $604 | Fulton Grace |
| Average Days on Market | 45 | Fulton Grace |
| Active Listings | 195 | Fulton Grace |
| Active Listings + Early Access | 108 + 15 | Redfin |
| Zillow Typical Value, 60614 | $676,448 | Zillow |
| Chicago Citywide Median List | ~$375,500 to $378,000 | Redfin |
What the Numbers Tell Us
- Medians vs. averages: The ~$1M average sits above the ~$894K median because luxury single-family listings ($3M to $10M) pull the average up.
- Zillow’s lower figure reflects a typical value across all homes, including older condos that are not currently listed.
- Lincoln Park costs roughly 2.4x the Chicago median, a premium that buyers pay for location, schools, and lakefront access.
Our hands-on deal analysis suggests that homes for sale Lincoln Park Chicago are pricing more like a premium asset class than a typical urban market. That matters when you weigh a home purchase against reinvesting sale proceeds into another business.
Lincoln Park vs. Nearby Neighborhoods
Buyers rarely search one neighborhood alone. Here is how Lincoln Park compares with its neighbors on current listing medians.
| Neighborhood | Redfin Median List Price | Zillow Typical Value | Positioning vs. Lincoln Park |
|---|---|---|---|
| Lincoln Park | $894,068 (sale median) | $676,448 (60614) | Benchmark |
| Roscoe Village | $925,000 | $707,908 | Similar pricing, more single-family |
| Bucktown | $884,000 | $682,095 | Comparable, younger buyer base |
| Wicker Park | $799,900 | $725,999 | Slightly lower, nightlife-driven |
| Logan Square | $750,000 | N/A | Lower entry, rising demand |
| Gold Coast | $699,000 | $430,409 | More high-rise condo stock |
| West Loop | $579,900 | N/A | Newer condos, office proximity |
| Lake View | $550,000 | $466,336 | Best value alternative nearby |
Key insight: Lake View offers the most direct value play for buyers priced out of Lincoln Park. Gold Coast offers doorman high-rise living at a lower median, though HOA dues often run higher.
Property Type Breakdown
Lincoln Park inventory is diverse. We evaluated current listings across Fulton Grace, Zillow, and Redfin to build this breakdown.
| Property Type | Typical Price Range | Real Listing Examples (Fall 2026) | Best For |
|---|---|---|---|
| Studio / 1-Bed Condo | $189K to $490K | 2650 N Lakeview #303 ($189,000); 2112 N Seminary #18 ($315,000) | First-time buyers, investors |
| 2-Bed Condo | $340K to $850K | 2717 N Wilton #3S ($675,000); 920 W Wrightwood #2 ($775,000) | Young professionals, downsizers |
| Duplex Condo | $600K to $1.5M | 1651 N Dayton #104 ($849,000); 2745 N Greenview #1 ($1,475,000) | Families wanting house-like space |
| Penthouse / New Construction | $1.0M to $2.9M | 2026 N Orleans PHS ($1,949,000); 1834 N Hudson #2 ($2,899,000) | Move-up buyers, executives |
| Townhome | $850K to $1.3M | 2730 N Greenview Unit M ($850,000) | Buyers wanting gated privacy |
| Single-Family Home | $1.2M to $10M | 907 W Fullerton ($1,200,000); 2714 N Magnolia ($3,299,990) | Established families, post-exit owners |
| Multi-Unit / Income Property | $2M to $7M+ | 2700 N Lakeview ($6,995,000, $414K annual rent) | Investors, multigenerational buyers |
The Income Property Angle
The 2700 N Lakeview listing stands out to us. It generates $414,000 in annual rental income ($18,000 + $16,500 monthly). At a $6,995,000 ask, that is roughly a 5.9% gross yield before expenses.
For business owners, that profile looks a lot like an acquisition: verified cash flow, tenant risk, and exit flexibility. We apply the same thinking to homes for sale Lincoln Park Chicago that we apply to a business purchase, starting with the actual income and working backward to price.
Price Range Distribution
Here is how listings cluster by price band, based on our review of active inventory this fall.
| Price Band | Share of Inventory (Approx.) | Typical Product | Buyer Competition |
|---|---|---|---|
| Under $400K | ~12% | Studios, 1-beds, older high-rises | High, especially from first-time buyers |
| $400K to $700K | ~25% | 2-bed condos, smaller duplexes | High |
| $700K to $1M | ~23% | Larger 2 to 3-bed units, townhomes | Moderate to High |
| $1M to $2M | ~22% | Duplexes, penthouses, new construction | Moderate |
| $2M to $4M | ~12% | Single-family, luxury triplexes | Selective |
| Over $4M | ~6% | Estates, landmark homes | Low, longer marketing times |
Watch the top end. The 2026 N Kenmore estate at $9,995,000 has sat 953 days on Zillow. Meanwhile, 2658 N Mildred at $3,998,000 shows 37 days. Pricing discipline, not just quality, drives speed at the luxury level.
HOA Fees: The Hidden Cost Buyers Miss
HOA dues can swing your monthly payment by thousands per year.
Lenders count them in your debt-to-income ratio, which matters if you also plan to carry business debt.
| Listing | Price | Monthly HOA | Notes |
|---|---|---|---|
| 2032 N Burling #3 | $1,050,000 | $160 | Small boutique building |
| 1357 W Fullerton Unit B | $600,000 | $186 | Parking included |
| 1833 N Larrabee #2 | $1,049,000 | $268 | Garage, newer build |
| Orleans Collection (4-bed) | $1,849,000 | $300 | New construction |
| 1834 N Hudson #2 | $2,899,000 | $350 | Triplex penthouse |
| 2202 N Clybourn #3 | $425,000 | $390 | 2 parking spots |
| 2525 N Sheffield #3E | $489,000 | $456 | 1922 loft building |
| 317 W Webster #1 | $699,000 | $497 | East Lincoln Park |
| 2700 N Hampden Ct #8B | $419,900 | $1,036 | Pool, built 1971 |
Rule of thumb from our team: A $1,036 HOA on a $420K condo carries roughly the same monthly cost as an additional $150K to $170K of mortgage principal at typical rates. Always compare total monthly cost, not just list price.
Buyer Action Steps
Our team has guided buyers through competitive markets for 15+ years. Here is the sequence we recommend for homes for sale Lincoln Park Chicago.
- Get fully underwritten preapproval. A letter based on a soft credit pull will not compete in the $700K to $1.5M range.
- Decide condo vs. duplex vs. single-family early. Each carries different HOA, tax, and maintenance profiles.
- Request the condo association documents before writing an offer: budget, reserve study, special assessments, and rental restrictions.
- Verify school boundaries directly with Chicago Public Schools. Listing language is not a guarantee.
- Review property tax history. Cook County reassessments can shift your monthly cost significantly.
- Watch early access and “coming soon” listings. Redfin shows 15 early access homes right now, which means some inventory never hits open market competition.
- Budget for closing costs and transfer taxes (see the table below).
- Align your purchase with any business transaction so your liquidity and credit are not stretched at the wrong moment.
Estimated Buyer Closing Costs on an $894K Purchase
| Cost Item | Estimated Range | Notes |
|---|---|---|
| Down Payment (20%) | ~$178,800 | Avoids PMI on most loans |
| Lender Fees & Points | $3,000 to $9,000 | Varies by loan type |
| Title & Escrow | $2,500 to $4,500 | Includes owner’s policy in some deals |
| Attorney Fees | $800 to $1,500 | Standard in Illinois closings |
| City of Chicago Transfer Tax (buyer) | ~$6,700 | Historically $3.75 per $500; verify current rate |
| Prepaid Taxes & Insurance | $8,000 to $15,000 | Depends on closing date |
| Inspection & Appraisal | $1,000 to $2,000 | Higher for single-family |
Transfer tax rates change periodically, so confirm current figures with your attorney before closing.
Check Also: How 5064 S Merrimac Ave Chicago IL 60638 Factors Into Cook County Business Valuation and Deal Strategy
Seller Tips: How to Price and Position in 2026
Sellers benefit from rising prices, but buyers still punish overpricing.
Here is what our team observed across current inventory.
Seller Strategy Checklist
- Price to the median band, not the outlier. A 2-bed condo should be priced against recent 2-bed sales, not the neighborhood average.
- Lead with outdoor space. Listings with rooftop decks, private terraces, and walled yards dominate the headlines.
- Name the school zone if it is a draw.
- Disclose HOA reserves and recent capital projects. Buyers and lenders ask anyway.
- Stage for scale. Duplex sellers who frame their unit as “living like a single-family home” are getting strong traffic.
- Time the market. Fall listings in Lincoln Park still see active open house calendars, as shown by dozens of Saturday and Sunday showings this week.
Buyer vs. Seller Responsibilities
| Responsibility | Buyer | Seller |
|---|---|---|
| Earnest Money Deposit | ✓ | |
| Home Inspection | ✓ | |
| Appraisal | ✓ (via lender) | |
| Condo Documents (22.1 Disclosure) | ✓ | |
| Residential Property Disclosure | ✓ | |
| City of Chicago Transfer Tax | ✓ (primary share) | ✓ (CTA portion) |
| State & County Transfer Tax | ✓ | |
| Water Certification | ✓ | |
| Title Commitment | Shared (often seller-paid) | ✓ |
| Property Tax Proration | Credit received | Credit paid |
Financing Considerations for Lincoln Park Buyers
At this price level, financing structure often matters more than rate. Here is how common loan types line up against Lincoln Park pricing.
| Loan Type | Best Fit Price Range | Down Payment | Key Consideration |
|---|---|---|---|
| Conventional Conforming | Under the current FHFA limit | 3% to 20% | Check the current Cook County conforming limit |
| Jumbo Loan | ~$800K and up | 10% to 20%+ | Stricter reserves and DTI rules |
| FHA | Lower-priced condos | 3.5% | Condo building must be FHA-approved |
| Portfolio / Private Bank | $2M and up | 20% to 30% | Flexible for self-employed buyers |
| Bridge Loan | Any | Varies | Useful when selling a home or business at the same time |
Special Notes for Business Owners
Self-employed buyers face a different underwriting path. Lenders typically want two years of tax returns, year-to-date profit and loss statements, and proof that business income is stable.
Here is where business and real estate intersect:
- SBA loan collateral: When buying a business, SBA lenders may take a lien on personal real estate if business collateral falls short. A new Lincoln Park home can become part of that conversation.
- Debt-to-income stacking: A jumbo mortgage plus a personal guarantee on business debt can limit your borrowing capacity.
- Liquidity timing: Closing a business sale before a home purchase often strengthens your file. Closing after can delay the home deal.
- Seller financing in your business sale may reduce the cash you have available for a down payment.
Chicagoland dealmakers are noting a clear pattern: owners who map out both transactions together close smoother. When we model homes for sale Lincoln Park Chicago for exiting owners, we always build the business sale timeline first.
Business Owner Scenarios: Coordinating Home and Business Deals
| Scenario | Recommended Sequence | Why It Works |
|---|---|---|
| Selling your business, buying a home | Close the business sale first | Cash proceeds and clean income documentation strengthen the mortgage file |
| Buying a business, buying a home | Secure home financing first, then SBA loan | Mortgage underwriting can be harder once new business debt appears |
| Healthcare practice sale + home upgrade | Structure earnout and consulting income carefully | Lenders may not count earnout income as stable |
| Buying income property in Lincoln Park | Treat it like an acquisition | Analyze rent rolls, expenses, and cap rate before price |
| Relocating a home-based business | Confirm zoning and HOA rules | Some associations restrict client visits and signage |
Our 25+ years in healthcare practice sales show that physicians and dentists often underestimate how lenders treat post-sale income. If you plan to purchase in Lincoln Park after a practice sale, talk with us before you sign a purchase contract.
Pros and Cons of Buying in Lincoln Park Now
Pros
- Strong appreciation trend (+24.2% YoY median)
- Diverse inventory from $189K studios to $10M estates
- Top-rated school zones and lakefront access
- Walkable retail and transit
- Income property options with verified rent rolls
Cons
- Premium pricing roughly 2.4x the Chicago median
- High HOA dues in some full-amenity buildings
- Property tax uncertainty with Cook County reassessments
- Competition in the $400K to $1M range
- Luxury overpricing leading to long days on market at the top end
FAQs
What is the median price of homes for sale in Lincoln Park Chicago?
Redfin reports a median sale price of $894,068 for August 2026, up 24.2% year over year. Fulton Grace shows an average home price near $1M at $604 per square foot.
How many homes are currently for sale in Lincoln Park?
Fulton Grace lists about 195 properties, while Redfin shows 108 active homes plus 15 early access listings. Counts vary by platform and date.
How long do Lincoln Park homes stay on the market?
The average is about 45 days, though well-priced condos often move faster and luxury estates can sit for months or even years.
What is the cheapest property available in Lincoln Park?
Current listings start around $189,000 for a studio condo at 2650 N Lakeview Avenue.
Are there income-producing properties in Lincoln Park?
Yes. The landmark property at 2700 N Lakeview is listed at $6,995,000 and generates $414,000 in annual rental income.
Should I sell my business before buying a Lincoln Park home?
In most cases, yes. Closing your business sale first gives lenders clear proceeds and income documentation. Our team can help you sequence both deals when reviewing homes for sale Lincoln Park Chicago alongside your exit plan.
Can a home purchase affect my SBA loan?
It can. SBA lenders review personal financial statements and may take liens on personal real estate. A new mortgage also affects your debt-to-income ratio.
Which Lincoln Park schools appear most in listings?
Alcott Elementary, Prescott Elementary, Oscar Mayer, and Lincoln Park High School appear frequently. Always verify boundaries with Chicago Public Schools.
Final Word From Chicagoland Business Broker
Lincoln Park remains one of Chicago’s most resilient and sought-after neighborhoods, and the 2026 data proves it. Rising medians, tight inventory, and a deep mix of property types create real opportunity for both buyers and sellers. But at these price points, every decision connects to your broader financial picture.
At Chicagoland Business Broker, we bring on-site business appraisals, loan negotiation support, and licensed real estate integration to every client conversation. Whether you are selling a company, buying a practice, or weighing homes for sale Lincoln Park Chicago after an exit, our team helps you build a plan where each transaction supports the next.
Reach out to us before you sign anything, and let’s make both deals work in your favor.
One Comment